Higher borrowing costs are putting renewed pressure on American households and businesses as rising bond yields push mortgage rates above 7% and keep affordability at the forefront of the U.S. economic debate.
The average rate on a 30-year fixed mortgage rose above 7% this week, reaching 7.03%, according to Freddie Mac, while the Mortgage Bankers Association reported an average of 7.12% for the week ended Sept. 18. The increase follows several weeks of rising rates and represents another setback for prospective homebuyers already facing elevated housing prices.
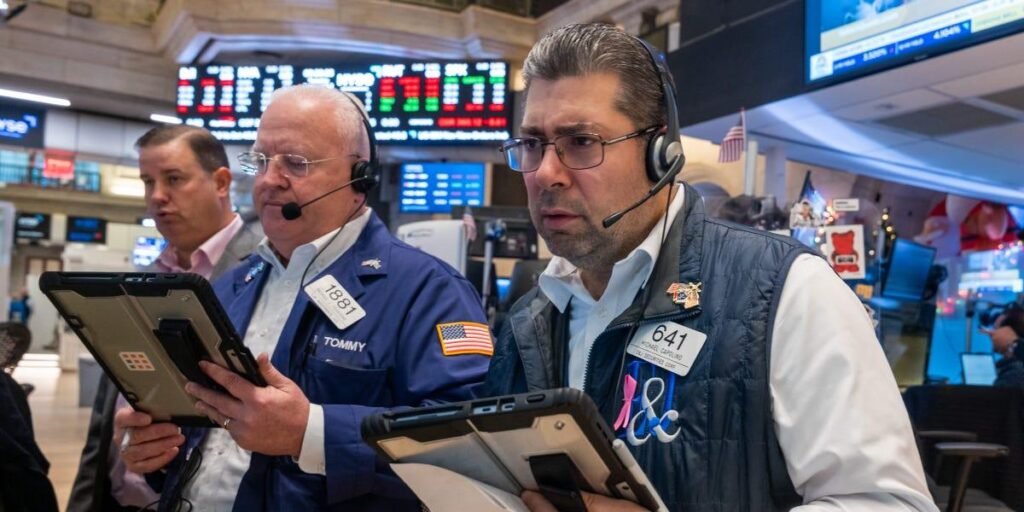
The rise in mortgage costs is closely connected to the bond market. The yield on the benchmark 10-year U.S. Treasury note has moved above 5%, increasing the cost of longer-term borrowing across the economy. Economists have pointed to persistent inflation, government borrowing, strong consumer spending and large investments in artificial-intelligence infrastructure as factors contributing to higher long-term interest rates.
The Federal Reserve has also raised its benchmark interest rate amid continued inflation concerns. While the central bank controls short-term rates, mortgage rates are influenced heavily by longer-term Treasury yields and broader expectations for inflation and economic growth. That means presidential calls for lower interest rates do not necessarily translate into cheaper mortgages for consumers.
The combination of higher housing costs, elevated prices for everyday goods and increased borrowing expenses has made affordability an increasingly prominent economic issue heading into the November midterm elections. Recent reporting has highlighted the potential political significance of those pressures, while polling has also shown that the cost of living remains an important concern for voters.
For households, the effects extend beyond prospective homeowners. Higher interest rates can raise financing costs for businesses, increase the cost of consumer credit and influence investment decisions across the economy. At the same time, a growing economy and continued investment in areas such as artificial intelligence are creating demand for capital, contributing to the unusual combination of economic growth alongside elevated borrowing costs.
The immediate economic question is whether inflation and other pressures ease enough to bring longer-term interest rates down, or whether elevated borrowing costs become a more persistent feature of the U.S. economy. For Americans already confronting higher housing and everyday expenses, the direction of rates will remain an important factor in household finances through the remainder of 2026.
Sources: The New York Times, The Hill, CNN, Reuters, Associated Press.